

Table of Contents
Premium Bonds vs a cash ISA comes down to certainty versus a prize draw. A cash ISA is the better choice for most savers: it pays a known, tax-free interest rate, and some cash ISAs pay more than the 4.35% Premium Bonds prize fund rate (Moneybox's, for example, pays 4.86% AER including a 12-month bonus) (Moneybox; NS&I). Premium Bonds win once you have used your £20,000 ISA allowance and pay higher- or additional-rate tax, or when you are saving for a child under 16 (GOV.UK; GOV.UK).
The 4.35% prize rate is an average, not what a typical holder receives. Our simulation of NS&I's published November 2026 prize table puts the median 12-month return on £20,000 at about 3.6%, and a £1,000 holder has roughly a 56% chance of winning nothing in a year (model and assumptions below). NS&I was in the news this week after The Independent reported on 17 November 2026 that it had reclaimed around £518,000 of duplicate prize payments made to about 3,500 Direct Saver accounts in May (The Independent).
Last updated: 18 November 2026. Rates, prize table, odds and eligibility re-checked against NS&I, Moneybox, GOV.UK and FSCS pages on this date. Figures in pounds sterling (£) for UK savers; tax figures use the 2026/27 tax year.
Key Takeaways
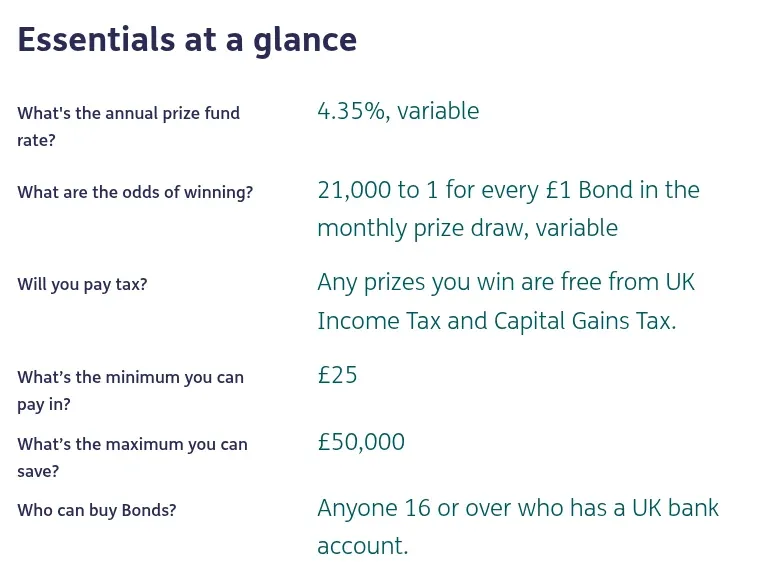
- Premium Bonds pay no interest: a 4.35% variable prize fund rate funds a monthly draw, with odds of 21,000 to 1 per £1 Bond, from £25 up to a £50,000 holding (NS&I).
- Cash ISAs pay tax-free interest on up to £20,000 a year in 2026/27; you must be 18 or over and UK resident to open one (GOV.UK).
- 98.7% of the 6,575,175 prizes in the November 2026 draw were £25, £50 or £100 prizes (NS&I prize allocation).
- On £20,000 for 12 months, a 4.86% cash ISA would pay £972, NS&I's 3.80% Direct ISA £760, and Premium Bonds £870 on average but a modelled median of £725 (worked example).
- The Budget on 28 October 2026 kept the £20,000 cash ISA limit and set savings tax rates of 24%, 44% and 49% from 6 April 2027, subject to legislation (Budget 2026).
Premium Bonds vs cash ISA at a glance
The table compares the two products' rules and returns. Every row links to the NS&I, provider or GOV.UK page it was read from on 18 November 2026.
| Item | Premium Bonds | Cash ISA |
|---|---|---|
| Our pick: Cash ISA | Second home for cash once the ISA allowance is used, or for gifts to under-16s (NS&I) | Default for most savers: known rate, tax-free interest (GOV.UK) |
| How you earn | Monthly prize draw, £25 to £1 million; no interest (NS&I) | Interest at a rate set by each provider; NS&I's Direct ISA rate is variable (NS&I Direct ISA) |
| Current rate (variable) | 4.35% prize fund rate from the September 2026 draw (NS&I) | Examples: NS&I Direct ISA 3.80% AER; Moneybox 4.86% AER incl. 1.16% 12-month bonus (NS&I; Moneybox) |
| Tax | Prizes free of UK Income Tax and Capital Gains Tax (NS&I) | Interest tax-free and outside the Personal Savings Allowance (NS&I; GOV.UK) |
| How much | £25 minimum per purchase; £50,000 maximum holding (NS&I) | £20,000 ISA allowance per tax year across all ISAs (GOV.UK) |
| Who can open | 16+ with a UK bank account; parents or guardians can hold for under-16s (NS&I) | 18+ and UK resident; Junior ISA for under-18s (GOV.UK) |
| Protection | 100% backed by HM Treasury (NS&I) | FSCS up to £120,000 per person per bank; NS&I's ISA is Treasury-backed (FSCS; NS&I) |
| Access | Cash in any time, no penalty; 3–5 days to your bank; new Bonds wait a full month before entering a draw (NS&I) | Depends on the account; NS&I Direct ISA: no notice or penalty, 3–5 days (NS&I) |
Two patterns stand out. First, both are tax-free, so the contest is really a guaranteed rate against a lottery-style average that most holders do not reach. Second, the two have different limits and age rules, which is why using both can make sense.
What is the difference between Premium Bonds and a cash ISA?
The difference between Premium Bonds and a cash ISA is how you are paid. A cash ISA pays interest on your balance at a stated rate, while Premium Bonds pay no interest and instead enter each £1 Bond into a monthly prize draw funded by the annual prize fund rate (NS&I Direct ISA; NS&I Premium Bonds).
Premium Bonds are a single product from NS&I, which is backed by HM Treasury. A cash ISA is a tax wrapper that many banks, building societies and apps offer, so rates and withdrawal rules vary by provider (GOV.UK).
Which pays more: Premium Bonds or a cash ISA?
A good cash ISA pays more than Premium Bonds for a typical saver, and a weak one pays less. The worked example below puts £20,000 into each option for 12 months, assuming today's variable rates do not change and no money is added or withdrawn.
| Option | Rate and conditions | Return on £20,000 |
|---|---|---|
| Moneybox Cash ISA (intro rate) | 4.86% AER incl. 1.16% bonus for 12 months; needs a £500+ balance and fewer than four withdrawals a year; transfers in get 3.70% (Moneybox) | £972 |
| Moneybox Open Access Cash ISA | 4.50% AER incl. 1.00% bonus; unlimited withdrawals (Moneybox) | £900 |
| Premium Bonds: average | 4.35% prize fund rate; the mean across all holders, not a forecast (NS&I) | £870 |
| NS&I Direct ISA | 3.80% AER; Treasury-backed; no transfers in (NS&I) | £760 |
| Premium Bonds: modelled median | Stablecoin Insider simulation (see below); middle 80% of outcomes £425 to £1,225 | £725 |
All five returns above are tax-free. The cash ISA figures are the stated AER multiplied by £20,000; Moneybox shows the same arithmetic on £1,000 (£1,048.60 at 4.86%) (Moneybox). Bonus rates expire after 12 months, after which Moneybox's standard cash ISA drops to its 3.70% underlying rate.
How likely are you to win on Premium Bonds?
You are likely to win small prizes on Premium Bonds if you hold a few thousand pounds, but unlikely to win a large one. With odds of 21,000 to 1 per £1 Bond per draw, £20,000 of Bonds can expect about 11 prizes a year, and almost all prizes are £25 to £100 (NS&I; NS&I prize allocation).
November 2026 Premium Bonds draw (prize counts from NS&I; shares calculated by Stablecoin Insider from the 6,575,175 total prizes worth £500,535,100):
| Prize value | Number of prizes | Share of all prizes |
|---|---|---|
| £1 million | 2 | 0.00003% |
| £5,000 to £100,000 | 3,557 | 0.05% |
| £1,000 | 20,020 | 0.30% |
| £500 | 60,060 | 0.91% |
| £100 | 2,381,417 | 36.22% |
| £50 | 2,381,417 | 36.22% |
| £25 | 1,728,702 | 26.29% |
NS&I allocates 80% of the prize fund to the £25, £50 and £100 band, 10% to £500 and £1,000 prizes, and 10% to prizes of £5,000 and above (NS&I). That is why the average return is pulled up by rare big wins while the typical holder earns less.
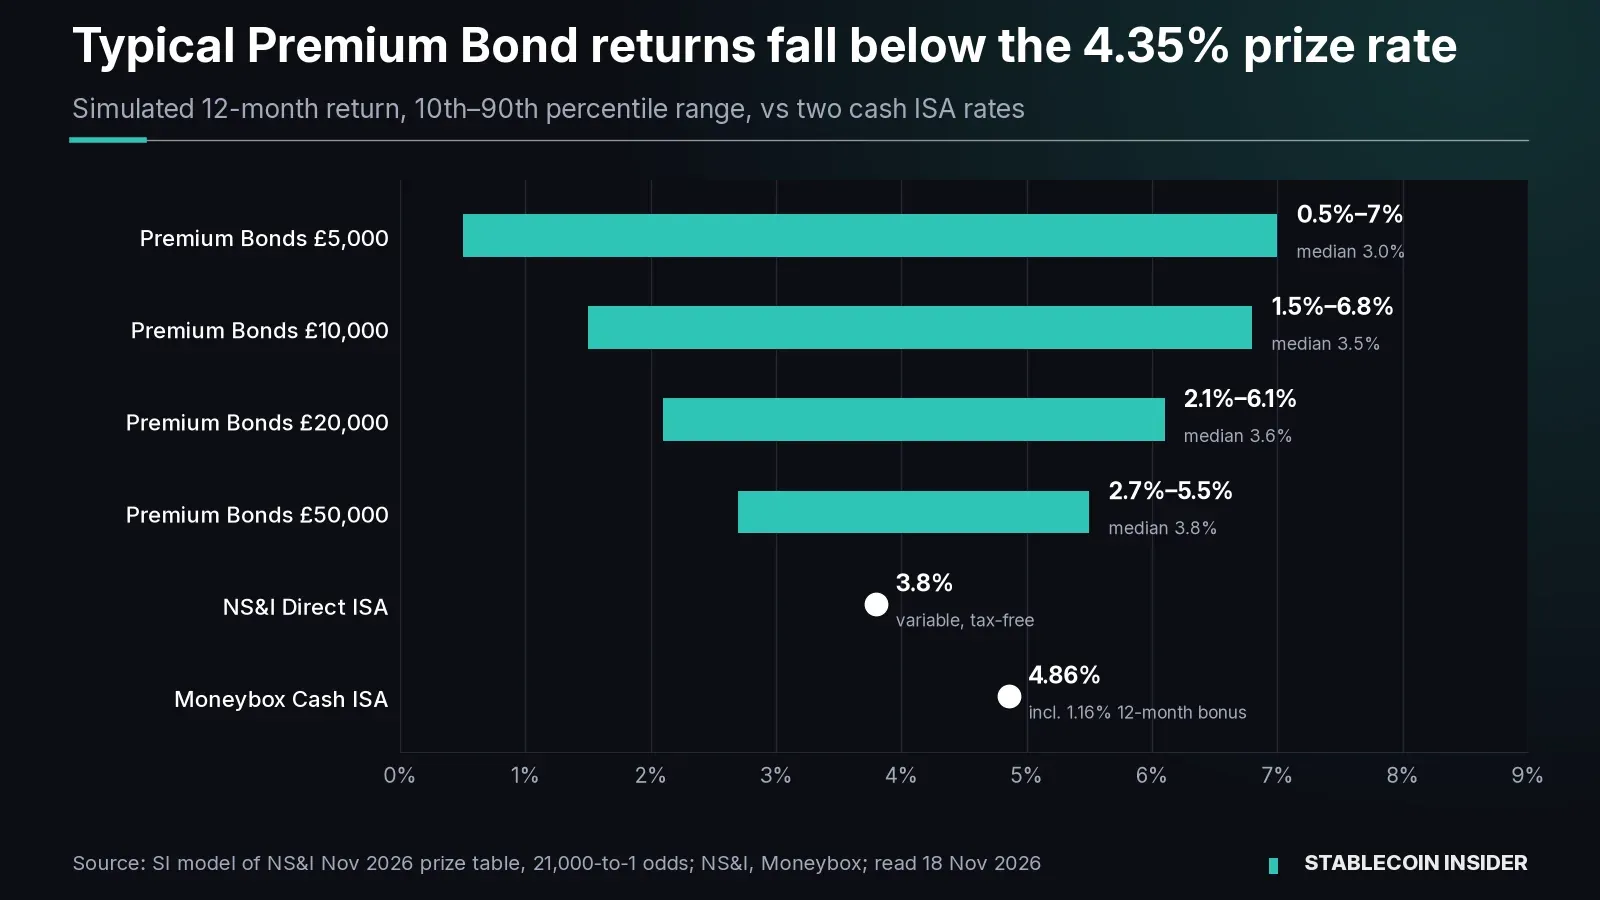
How we modelled it: we simulated 500,000 holders at each balance for 12 draws, using the 21,000-to-1 odds and the prize mix of the November 2026 draw, and assumed both stay the same all year. The model reproduces the 4.35% average, and gives these medians: 3.0% on £5,000, 3.5% on £10,000, 3.6% on £20,000 and 3.8% on £50,000. A £20,000 holder has about a 13.5% chance of at least one prize of £500 or more in a year. These are statistical estimates, not predictions; real draws vary and NS&I can change the rate, odds and prize mix at any time.
When do Premium Bonds beat a cash ISA?
Premium Bonds beat a cash ISA mainly when the ISA is not available to you: your £20,000 allowance is already used, you are under 18, or the money is for a child. In those cases the real alternative is a taxable savings account, and tax changes the maths (GOV.UK).
Outside an ISA, interest above your Personal Savings Allowance is taxed. The allowance is £1,000 for basic-rate, £500 for higher-rate and £0 for additional-rate taxpayers, and the Income Tax rates are 20%, 40% and 45% (GOV.UK savings allowance; GOV.UK Income Tax rates).
Take £50,000 that cannot go into an ISA this year, in NS&I's Direct Saver at 3.75% gross (NS&I). That pays £1,875 before tax. Assuming no other savings interest and no starting rate for savings, a basic-rate taxpayer keeps £1,700, a higher-rate taxpayer £1,325 and an additional-rate taxpayer about £1,031. The same £50,000 in Premium Bonds has a modelled median of £1,900, tax-free, though the outcome is uncertain (middle 80%: £1,350 to £2,725).
The gap widens from 6 April 2027 if Parliament passes the Budget measure raising savings tax rates to 24%, 44% and 49% (Budget 2026).
Who should choose a cash ISA?
A cash ISA suits savers who want a predictable return and have unused ISA allowance. It also suits smaller balances: on £1,000 of Premium Bonds there is roughly a 56% chance of no prize in a year (our calculation from the 21,000-to-1 odds), while a cash ISA pays interest on every pound (NS&I).
Limitations: headline rates often include short bonuses and withdrawal limits, as with Moneybox's four-withdrawal rule (Moneybox). Some accounts, including NS&I's Direct ISA, are not flexible, so money you withdraw still counts towards that year's allowance (NS&I). Bank-held deposits are protected by the FSCS up to £120,000 per person per authorised firm (FSCS).
Who should choose Premium Bonds?
Premium Bonds suit savers who have filled their ISA, pay higher or additional rate tax, and are comfortable with an uncertain return in exchange for tax-free prizes and full Treasury backing. You can also buy them as a gift for a child under 16, with a parent or guardian managing the Bonds until the child turns 16 (NS&I).
Limitations: there is no guaranteed return, no regular income and no joint holding, NS&I says, and new Bonds sit out a full calendar month before their first draw (NS&I). Inflation can erode the real value of money held in either product, a point NS&I makes on its Premium Bonds page.
Weighing up other UK money decisions? See our comparison of UK SIPP providers on fees, and if your bank is changing, our guides to TSB alternatives and Metro Bank alternatives.
Comparing cash savings with on-chain yield? For the full picture, see our Stablecoin yield hub.
FAQ
Can I have Premium Bonds and a cash ISA at the same time?
Do Premium Bond prizes count towards my Personal Savings Allowance?
How quickly can I get my money out of Premium Bonds or a cash ISA?
Which accounts were affected by the NS&I duplicate prize payment error?
When are the next Premium Bonds results?
Verdict: Premium Bonds or a cash ISA?
Pick a cash ISA first if you have allowance left and want a known return: a cash ISA paying more than 4.35%, such as Moneybox's 4.86% introductory rate, beats both the Premium Bonds average and our modelled median. Pick Premium Bonds for tax-free savings beyond the £20,000 allowance, particularly as a higher- or additional-rate taxpayer, or as a gift for a child under 16. Holding both is allowed.
Sources: NS&I Premium Bonds, NS&I prize allocation (November and December 2026 draws), NS&I press release PR260818, 18 August 2026, NS&I Direct ISA, NS&I Direct Saver, Moneybox Cash ISA, GOV.UK: Individual Savings Accounts, GOV.UK: Tax on savings interest, GOV.UK: How much savings interest is tax free, GOV.UK: Income Tax rates, HM Treasury: Budget 2026, FSCS deposit protection limit, The Independent, 17 November 2026; all read on 18 November 2026.
This content is provided for informational and educational purposes only and doesn't constitute financial, investment, legal or tax advice. Rates, odds and prize figures were read on 18 November 2026 and are variable; the Premium Bonds return ranges are statistical estimates from a Stablecoin Insider model, not guarantees. Tax treatment depends on your circumstances. Organisations and products mentioned: NS&I, Premium Bonds, NS&I Direct ISA, NS&I Direct Saver, Moneybox, HM Treasury, HMRC, FSCS.


