

Table of Contents
The best pension providers in the UK for a self-invested personal pension (SIPP), on fees read on 17 November 2026, are InvestEngine if you only want ETFs (no account fee), Vanguard if you are happy with Vanguard's own funds (0.15% a year, capped at £375), and interactive investor if you have a larger pot and want a flat fee (£5.99 a month up to £100,000). AJ Bell suits people who want a full fund and share range at a lower percentage than most rivals, and PensionBee suits savers who want someone else to pick the investments and combine old pensions.
Searches for "pension" in the UK passed 100,000 on Google Trends' Business and Finance list in the past week. This guide compares seven personal pensions on what each charges, who it suits and where it falls short, with a worked fee calculation for four pot sizes. It covers personal pensions you open yourself, not workplace schemes.
Last updated: 17 November 2026. Account fees, dealing charges and eligibility re-checked against each provider's own pages on this date.
Key Takeaways
- InvestEngine charges no SIPP account fee for DIY ETF portfolios; its managed portfolios cost 0.25% a year, and ETF costs apply in both cases (InvestEngine costs).
- Vanguard charges £4 a month on invested balances under £32,000, then 0.15% a year capped at £375, but you build the portfolio from Vanguard's own funds (Vanguard Personal Pension; Vanguard fees).
- interactive investor's flat £5.99 Core plan covers portfolios up to £100,000; above that you move to Plus at £14.99 a month (ii charges).
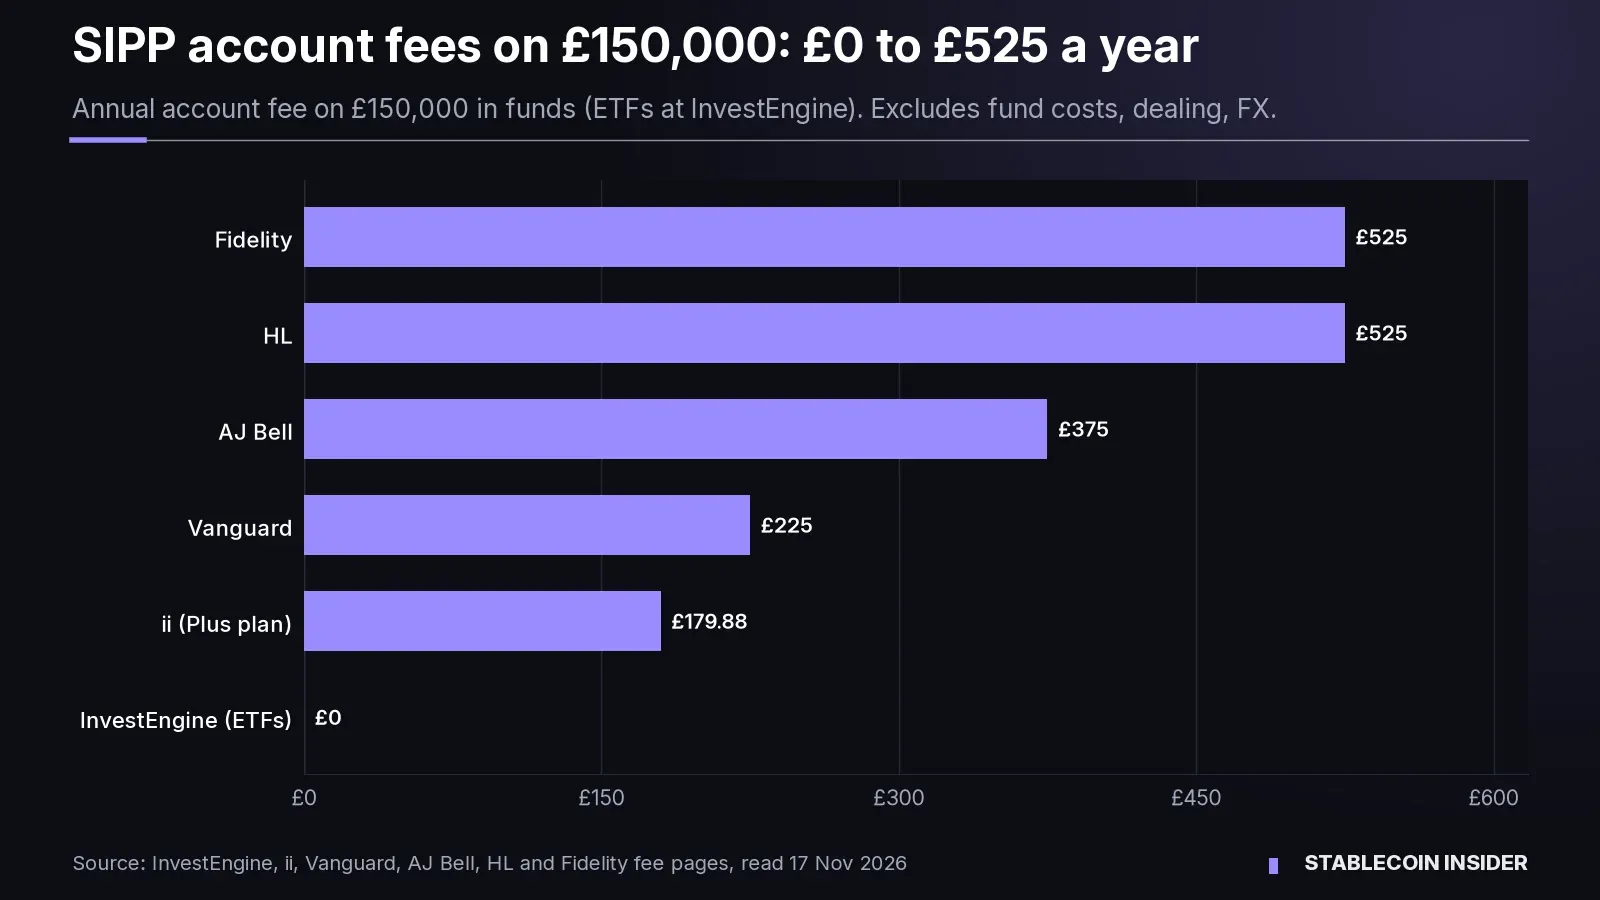
- On £150,000 held in funds, the yearly account fee in our worked example runs from £179.88 (ii) to £525 (Hargreaves Lansdown and Fidelity) among platforms that offer funds, before fund charges.
- PensionBee charges one all-in fee of 0.50% to 0.95% a year, halved on savings above £100,000, and a £150 fee if you withdraw everything within your first year (PensionBee fees).
Which are the best pension providers in the UK in 2026?
The best pension providers in the UK in 2026 differ by what you hold and how much. Percentage fees favour small pots; flat and capped fees favour large ones. The table lists each provider's headline SIPP account fee and its best fit, with every row linked to the fee page it was read from.
| Provider | Account fee (as published) | Holdings and best fit |
|---|---|---|
| Our pick: InvestEngine | £0 on DIY; 0.25% managed | ETFs only; UK residents 18–75. Best for low-cost ETF investors |
| Vanguard | £4/month below £32,000, then 0.15% (max £375) | Vanguard funds only. Best for hands-off fund investors |
| interactive investor | £5.99/month to £100,000; £14.99 above | Funds, shares, ETFs, trusts. Best for pots above about £50,000 |
| AJ Bell | Funds 0.25% (tiered); shares 0.25%, max £10/month | Funds, shares, ETFs, trusts. Best for wide choice at a mid-range fee |
| Hargreaves Lansdown | Funds 0.35% (tiered); shares 0.35%, max £12.50/month | Funds, shares, ETFs, trusts. Best for research and service |
| Fidelity | 0.35% (£90/year flat below £25,000 without a savings plan); 0.20% from £250,000; shares max £90/year | Funds, shares, ETFs. Best for share and ETF holders |
| PensionBee | 0.50%–0.95% all-in; halved above £100,000 | Ready-made plans only. Best for combining old pensions |
Two patterns stand out. Every percentage fee in the table grows with your pot unless it is capped, so the ranking changes as you save more. And the lowest-fee options restrict what you hold: InvestEngine to ETFs and Vanguard to its own funds. PensionBee restricts you to six ready-made plans (PensionBee plans).
How much does each pension provider charge on £20,000 to £400,000?
Each provider charges between £0 and £1,250 a year in account fees on the pots below, before any fund charges. The figures are our calculation from each provider's published fee schedule, under these assumptions:
- One SIPP and no other accounts with the provider (Vanguard, Fidelity and ii combine accounts when they set your fee).
- All money invested, not in cash, and held either entirely in funds or entirely in shares, ETFs and investment trusts.
- Account or platform fee only. Fund ongoing charges, dealing, FX and stamp duty are excluded, as are introductory offers.
- Fidelity's £20,000 figure assumes a regular savings plan; without one the fee is £90. ii is on Core up to £100,000 and Plus above. Table figures are rounded to the nearest pound.
Yearly account fee if you hold funds (InvestEngine row: ETFs, as it offers no other funds; HL is Hargreaves Lansdown; provider names link to the fee schedule used):
| Provider | £20k | £60k | £150k | £400k |
|---|---|---|---|---|
| InvestEngine | £0 | £0 | £0 | £0 |
| Vanguard | £48 | £90 | £225 | £375 |
| ii | £72 | £72 | £180 | £180 |
| AJ Bell | £50 | £150 | £375 | £775 |
| Fidelity | £70 | £210 | £525 | £800 |
| HL | £70 | £210 | £525 | £1,250 |
Yearly account fee if you hold shares, ETFs or investment trusts:
| Provider | £20k | £60k | £150k | £400k |
|---|---|---|---|---|
| InvestEngine | £0 | £0 | £0 | £0 |
| Fidelity | £70 | £90 | £90 | £90 |
| AJ Bell | £50 | £120 | £120 | £120 |
| HL | £70 | £150 | £150 | £150 |
| ii | £72 | £72 | £180 | £180 |
The order flips with the asset type. In funds, ii's flat fee is the cheapest paid option from £60,000, and Vanguard's £375 cap keeps it low at £400,000. In shares and ETFs, the caps at Fidelity (£90 a year), AJ Bell (£120) and HL (£150) beat every percentage fee once the pot passes £60,000 (Fidelity; AJ Bell; HL).
PensionBee is not in these tables because its fee includes fund management. On its Tracker Plan (0.50%) the all-in cost would be £100 on £20,000 and £625 on £150,000; on the default Global Leaders Plan (0.70%) it would be £140 and £875 (PensionBee fees). Compare those numbers with a platform fee plus the fund charge you would pay elsewhere.
Which pension provider suits you best?
The pension provider that suits you best depends on what you want to hold, how often you trade and whether you want to choose investments at all. Each profile below covers fit, fees, eligibility and the main drawbacks.
1. InvestEngine: best for low-cost ETF investors
InvestEngine suits savers who are happy to build a pension from ETFs. It charges no SIPP account fee and no dealing fee on DIY portfolios; its managed portfolios cost 0.25% a year, and ETF charges apply on top, starting from 0.03% a year on DIY (InvestEngine costs). You can open it with £100, and regular contributions start at £20 a week or £50 a month (InvestEngine SIPP).
The limits are real. You can only hold ETFs, and the SIPP is open to UK residents aged 18 to 75 (InvestEngine SIPP). InvestEngine also says it keeps the interest on cash held with it (InvestEngine SIPP).
- Pros: no account or dealing fee on DIY; low minimums; managed option at 0.25%.
- Cons: ETFs only; UK residents only; interest on uninvested cash is retained by InvestEngine.
2. Vanguard Personal Pension: best for simple fund portfolios
Vanguard suits people who want a low, capped fee and are happy with one fund house. Its self-managed pension costs £4 a month on invested balances under £32,000, then 0.15% a year, capped at £375; Vanguard fund costs range from 0.06% to 0.79% a year (Vanguard Personal Pension). A managed version adds a 0.30% management fee (Vanguard).
Drawdown is available, and Vanguard says there are no hidden charges for withdrawals (Vanguard). The catch is choice: you build the portfolio from Vanguard's own funds, and its optional quote-and-deal service costs £7.50 per trade (Vanguard fees).
- Pros: £375 yearly cap; drawdown available; low-cost index funds.
- Cons: Vanguard products only; £48 minimum fee makes small pots relatively expensive (0.24% on £20,000).
3. interactive investor: best flat fee for larger pots
interactive investor suits savers whose pot has grown past the point where percentage fees bite. Its Core plan costs £5.99 a month for portfolios up to £100,000, Plus costs £14.99 a month with no limit, and Premium costs £39.99 (ii charges). The fee covers all accounts on the plan, including the pension.
Trading costs are separate. On Core, funds and UK or US shares cost £3.99 a trade and FX costs 0.75%; on Plus, fund trades drop to £1.49 (ii charges). ii says it will pay £100 to £5,000 cashback when you deposit or transfer at least £20,000 into the pension, subject to offer terms (ii SIPP).
- Pros: flat fee does not grow with the pot; full investment range; regular investing is free.
- Cons: £71.88 a year is high on a small pot (0.36% on £20,000); trading fees on top; Core is capped at £100,000.
4. AJ Bell: best all-rounder on price and choice
AJ Bell suits investors who want funds and shares in one pension at a lower percentage than HL or Fidelity. It charges 0.25% a year on the first £250,000 in funds, 0.10% on the next £250,000 and nothing above £500,000; shares, ETFs and trusts cost 0.25% capped at £10 a month (AJ Bell SIPP charges). Online fund deals cost £1.50 and share deals £5, or £3.50 after 10 or more deals in the previous month.
Flexi-access drawdown and pension lump sums carry no AJ Bell charge, and transfers out are free (AJ Bell). AJ Bell says it covers exit fees up to £500 on transfers in if your account is worth £20,000 or more (AJ Bell). Its schedule took effect on 10 July 2026.
- Pros: lower fund fee than HL and Fidelity; share fee capped at £120 a year; no drawdown charge.
- Cons: uncapped on funds up to £250,000, so large fund pots pay more than at Vanguard or ii.
5. Hargreaves Lansdown: best for research and service, at a price
Hargreaves Lansdown suits investors who want a large platform and are willing to pay more for it. It charges 0.35% on the first £250,000 in funds, 0.25% to £1 million, 0.10% to £2 million and nothing above that; shares and ETFs cost 0.35%, capped at £12.50 a month (HL SIPP charges). One-off fund trades cost £1.95 and share deals £6.95, or £3.95 after 20 trades in the previous month.
You can start from £25 a month or a £100 lump sum (HL SIPP). HL applies its fund tiers per account, so £200,000 in a SIPP and £200,000 in a separate HL account are each charged at 0.35% (HL).
- Pros: wide investment range; share fee capped at £150 a year; free regular investing.
- Cons: highest fund fee here, £525 a year on £150,000; tiers do not combine across accounts.
6. Fidelity: best for shares and ETFs inside a pension
Fidelity suits pension savers who mainly hold shares and ETFs. The 0.35% service fee on exchange-traded investments is capped at £7.50 a month, or £90 a year (Fidelity charges). On funds the fee is 0.35% from £25,000 and 0.20% from £250,000, applied across your whole balance; under £25,000 you pay 0.35% with a regular savings plan or £90 a year without one.
Fidelity charges nothing for capped or flexible drawdown administration or transfers out (Fidelity). Regular savings start at £20 a month, lump sums at £800, and it reimburses exit fees of up to £500 per customer on transfers in, subject to terms (Fidelity SIPP). Online share deals cost £7.50 (£1.50 in a regular plan).
- Pros: £90 yearly cap on shares and ETFs; no drawdown admin charge; 0.20% rate from £250,000.
- Cons: fund fee is 0.35% up to £250,000; £7.50 online share deals.
7. PensionBee: best for combining old pensions without picking funds
PensionBee suits people who want to merge old workplace pensions and leave the investing to someone else. It charges one annual fee from 0.50% (Tracker and Preserve) to 0.95% (Shariah), which it says covers fund management, transfers, switching and withdrawals, and halves the fee on savings above £100,000 (PensionBee fees).
You cannot pick individual funds; you choose one of six plans (PensionBee plans). If you withdraw your whole pot within the first year, a £150 fee applies. PensionBee says plan holdings are structured as long-term insurance contracts covered 100% by the FSCS if a money manager fails and a claim is accepted (PensionBee).
- Pros: one fee, no dealing charges; simple app; fee halves above £100,000.
- Cons: no DIY investing; the all-in fee is higher than a cheap platform plus an index fund; £150 early full-withdrawal fee.
What should you check before choosing a pension provider?
Before choosing a pension provider, check how its fee scales with your pot, what it lets you hold and what it charges when you start taking money out. Then check what your current scheme would cost you to leave.
- Annual allowance: tax relief applies to contributions up to £60,000 this tax year, or 100% of your earnings if lower; it can be lower for high earners (GOV.UK).
- Tax-free cash: you can usually take up to 25% as a tax-free lump sum, up to £268,275 in total (GOV.UK).
- Access age: personal pensions can normally be accessed from 55, rising to 57 from 2028 (Vanguard; PensionBee).
- Exit fees and guarantees: AJ Bell and Fidelity reimburse exit fees up to £500 on transfers in, subject to terms, but InvestEngine warns you may lose guarantees or features only your current provider offers (AJ Bell; Fidelity; InvestEngine).
Weighing a US retirement account instead? Our Robinhood vs Webull comparison covers IRA match offers. UK readers changing banks can see our Metro Bank alternatives, and if you move money abroad, Wise vs Revolut compares transfer costs. No Stablecoin Insider hub covers UK pensions yet, so this guide stands alone.
FAQ
Can I move an old workplace pension into a SIPP?
Can I have more than one SIPP?
Who is the cheapest pension provider in the UK?
How do I get higher-rate tax relief on a personal pension?
Verdict: which UK pension provider should you choose?
The UK pension provider you should choose depends mostly on pot size and asset type. For ETF investors, InvestEngine is our pick because it removes the account fee entirely. Fund investors with up to about £30,000 pay least at AJ Bell or Vanguard. Above £60,000, ii's flat fee and Vanguard's £375 cap pull ahead. Share-heavy portfolios fit Fidelity's £90 cap or AJ Bell's £120 cap. Choose PensionBee only if not picking investments is worth its higher all-in fee to you.
Sources: InvestEngine SIPP; InvestEngine costs; Vanguard fees explained; Vanguard Personal Pension; Vanguard: using your pension money; interactive investor SIPP charges; interactive investor SIPP; AJ Bell SIPP charges; AJ Bell SIPP charges schedule (PDF); Hargreaves Lansdown SIPP charges; Hargreaves Lansdown SIPP; Fidelity charges; Fidelity SIPP; PensionBee fees; PensionBee plans; GOV.UK annual allowance; GOV.UK lump sum allowance; Google Trends Trending Now, United Kingdom, Business and Finance, past 7 days. All read on 17 November 2026.
This content is provided for informational and educational purposes only and doesn't constitute financial, investment, legal or tax advice. Fees, plans, offers and eligibility for InvestEngine, Vanguard, interactive investor, AJ Bell, Hargreaves Lansdown, Fidelity and PensionBee were read from their own UK pages on 17 November 2026, are in GBP, apply to UK personal pensions and can change. Worked fee figures are Stablecoin Insider calculations under the stated assumptions and exclude fund, dealing and FX costs. Tax treatment depends on your circumstances and may change. The value of investments can fall as well as rise. Consider regulated financial advice before transferring a pension.


