Table of Contents
The best Metro Bank alternatives for most personal customers are Nationwide FlexDirect if you want a branch, first direct's 1st Account if you want the biggest switching payment and no card fees abroad, and Starling if you want an app bank with 24/7 support and Post Office cash deposits. Monzo suits budgeters, and Chase UK suits people who want cashback on everyday spending. All five charge no monthly fee on the accounts compared here, read on 16 November 2026.
People are looking because on 12 November 2026 Metro Bank Holdings PLC announced a strategic review that includes a formal sale process for the whole company, with Morgan Stanley as lead adviser (Metro Bank RNS). The bank also said it is not in active talks with any potential buyer, has not received an approach, and will keep running its standalone plan if no deal happens. A sale process does not, by itself, change how your deposits are protected; the section on safety below explains why.
Last updated: 16 November 2026. Fees, switch offers and eligibility re-checked against each bank's own pages on this date.
Key Takeaways
- Metro Bank says there "can be no certainty that any offer will be made", and it reaffirmed its targets of more than 13% return on tangible equity in Q4 2026 (Metro Bank RNS).
- Eligible deposits at Metro Bank PLC are protected by the FSCS up to £120,000 per person, the same limit that applies at each alternative below (Metro Bank; FSCS).
- Metro Bank charges a 2.99% non-sterling transaction fee on card spending abroad, plus £1.50 on each foreign cash withdrawal (Metro Bank). first direct, Starling, Monzo and Chase charge no fee of their own on card spending abroad.
- first direct pays £210 for a full switch on accounts opened between 14 September and 2 December 2026; Nationwide pays £175 (first direct; Nationwide).
- first direct deposits share one £120,000 FSCS limit with HSBC UK, HSBC Private Bank and M&S Bank, so check overlaps before you move a large balance (first direct).
Why are people looking for Metro Bank alternatives?
People are looking for Metro Bank alternatives because the bank put itself up for sale on 12 November 2026. Its board said it is reviewing options to "accelerate growth", including a formal sale process under the Takeover Code, and invited expressions of interest for the entire share capital (Metro Bank RNS). Investing.com reported that the process began even though no buyer had approached the bank (Investing.com).
Nothing in the announcement says accounts are closing or changing. Metro Bank's Q3 trading update on 4 November reported customer deposits of £13.0 billion and a net loan-to-deposit ratio of 71% (Metro Bank Q3 2026 update). Uncertainty about a future owner is still a fair reason to compare, as is cost: Metro Bank charges 2.99% on foreign-currency card payments (Metro Bank).
Branch access is the other factor. Metro Bank's opening-hours page listed 78 stores on 16 November 2026. None opened on Sundays, 34 opened on Saturdays, and weekday hours were 9.30am to 5pm (Metro Bank store hours). If you joined for seven-day branches, check your local store before assuming it still opens at weekends.
Metro Bank alternatives at a glance
The table compares Metro Bank's Current Account, the reference row, with five alternatives on card fees abroad, cash access and the current switch offer. None of the six charges a monthly fee on the account listed (Metro Bank; Nationwide; first direct; Starling; Monzo; Chase). Each cell links to the bank page it was read from on 16 November 2026.
| Account | Card fees abroad (bank's own) | Cash and in-person banking | Switch offer |
|---|---|---|---|
| Our pick: Nationwide FlexDirect (branch users) | 2.99% on purchases and cash (Nationwide) | 605 branches, kept open until at least start of 2030 (Nationwide) | £175 for a full switch (Nationwide) |
| Reference: Metro Bank Current Account | 2.99%; cash also £1.50 (Metro Bank) | 78 stores listed; up to £5,000 cash a day (store hours; account page) | None listed |
| first direct 1st Account | None from first direct (first direct) | No own branches; cash at HSBC UK counters or Post Office (first direct) | £210 (£175 + £35 boost) (first direct) |
| Starling | None from Starling; £300 daily cash limit (Starling) | Post Office: £1,000 a year free, then 0.7% (Starling) | None listed |
| Monzo | None on spending; cash rules below (Monzo) | PayPoint or Post Office, £1 per deposit (Monzo) | None listed |
| Chase UK | None from Chase (Chase) | App only; smartphone and UK mobile needed (Chase) | None listed |
Two patterns stand out. Nationwide is the only alternative here with its own large branch network, but its FlexDirect card carries the same 2.99% foreign fee as Metro Bank (Nationwide). The four app-led accounts drop that fee, but cash deposits move to the Post Office, PayPoint or another bank's counter, often with annual caps or per-deposit charges.
Which Metro Bank alternatives are best in 2026?
The best Metro Bank alternatives in 2026 depend on why you chose Metro Bank in the first place: branches, cash handling, or a no-fee everyday account. Each profile below states who it suits, what it does better or worse than Metro Bank, and the conditions that apply.
1. Nationwide FlexDirect: the closest branch-based swap
Nationwide FlexDirect is the closest swap for customers who value a branch. Nationwide says it has 605 branches, 154 of them the last in their town, and that every branch will stay open until at least the start of 2030, barring circumstances beyond its control (Nationwide).
FlexDirect has no monthly fee. For the first 12 months, paying in £1,500 a month earns 5% AER on balances up to £1,500, then 1% AER variable, plus up to £10 a month cashback: £5 for £300 of Direct Debits and £5 for £500 of card spending (Nationwide). The £175 switch payment needs a full switch through the Current Account Switch Service from a non-Nationwide, non-Virgin Money account, at least two Direct Debits, and £1,000 paid in plus one card payment within 31 days.
Worse than Metro Bank: the arranged overdraft costs 39.9% a year after the first £50 (38.2% APR representative), against Metro Bank's 34% APR typical rate (Nationwide; Metro Bank). FlexDirect also charges 2.99% abroad; only Nationwide's FlexPlus, FlexStudent, FlexGraduate and FlexOne cards avoid that fee (Nationwide).
- Pros: large branch network with a stated commitment to 2030; intro interest and cashback; £175 switch payment.
- Cons: 2.99% card fee abroad; intro rate only on the first £1,500 and only for 12 months; higher overdraft rate than Metro Bank.
2. first direct 1st Account: best switch payment, no fees abroad
first direct's 1st Account suits people who rarely need a branch and want the biggest switching payment. It pays £210 (£175 plus a £35 boost for accounts opened between 14 September and 2 December 2026) if, within 45 days, you switch with at least two Direct Debits or standing orders, deposit £1,000, make five card payments and log on to digital banking (first direct). The offer excludes anyone who has opened an HSBC current account since 1 January 2018.
It charges no first direct fees for card payments or cash withdrawals abroad, includes a £250 interest-free overdraft subject to status (30.5% APR representative on a £1,200 limit), and opens access to a 7% AER Regular Saver for £25 to £300 a month (first direct). first direct has no branches of its own, but you can pay in cash at HSBC UK branches with a counter, or use the Post Office or a Banking Hub (first direct).
- Pros: largest switch payment in this comparison; no first direct fees abroad; interest-free £250 overdraft buffer.
- Cons: no own branches; FSCS limit shared with HSBC UK, HSBC Private Bank and M&S Bank; offer excludes recent HSBC customers.
3. Starling: app bank with 24/7 support and Post Office cash
Starling suits people who want a full UK bank in an app, with 24/7 UK-based support by chat or phone (Starling). You need to live in the UK and be 18 or over. Starling charges no fees of its own to spend or withdraw abroad, up to a £300 daily cash limit, and says it passes the exchange rate on without adding fees of its own (Starling).
Cash is the trade-off for former Metro Bank store users. Starling personal accounts can pay in £1,000 a year free at the Post Office, then 0.7% on the excess, with a £5,000 yearly and £1,000 daily cap (Starling Help). Metro Bank allows up to £5,000 a day in store (Metro Bank).
- Pros: no monthly fee; no Starling fees abroad; 24/7 human support.
- Cons: no branches; cash deposits capped and charged above £1,000 a year; no switch payment listed.
4. Monzo: budgeting tools and cheap cash deposits
Monzo suits people who budget closely and still handle some cash. The free personal account includes Pots, a Salary Sorter and spending targets, and you can pay in cash at any PayPoint or Post Office for £1 per deposit (Monzo). Paid plans start at £3 a month; the £9 Perks plan unlocks 3.70% AER variable on Select Access Savings with a £500 minimum.
Monzo charges no foreign transaction fees on card spending. If Monzo is your main bank account, cash withdrawals are fee-free without limit in the European Economic Area and up to £200 every 30 days elsewhere, then 3% (Monzo). That condition matters if you keep Metro Bank as your main account while you try Monzo.
- Pros: strong budgeting features; £1 cash deposits at PayPoint and Post Office; no fees on card spending abroad.
- Cons: no branches; fee-free cash abroad depends on main-account status outside the EEA; best savings rate requires a paid plan.
5. Chase UK: cashback for everyday spending
Chase UK, a trading name of J.P. Morgan Europe Limited, suits app-first users who want cashback. It offers 2% cashback, up to £20 a month, on groceries, restaurants, cafes, takeaways, everyday transport, fuel and public EV charging, and requires both Chase current and saver accounts (Chase). To apply you must be 18 or over, a UK resident and UK tax resident with a smartphone and UK mobile number, and pass a soft credit search.
Chase charges no fees when you use your card abroad. Cash withdrawals are capped at £500 a day and, when abroad, £1,500 a calendar month (Chase). Cashback is not paid on purchases made outside the UK or the Channel Islands.
- Pros: cashback on common spending; no Chase fees abroad; no monthly fee.
- Cons: app only; no branches; cashback needs a saver account too and excludes spending abroad.
What does using your card abroad cost at Metro Bank vs the alternatives?
Using your card abroad costs £47.86 in bank fees at Metro Bank and £41.86 at Nationwide FlexDirect in our worked example, against £0 at first direct, Starling, Monzo and Chase. The assumptions: £1,000 of card spending in euros, plus four cash withdrawals worth £100 each from euro-area ATMs, over a year.
| Account | Card spending (£1,000) | Four £100 withdrawals | Total bank fees |
|---|---|---|---|
| Metro Bank | 2.99% = £29.90 (Metro Bank) | 4 × (£2.99 + £1.50) = £17.96 | £47.86 |
| Nationwide FlexDirect | 2.99% = £29.90 (Nationwide) | 4 × £2.99 = £11.96 | £41.86 |
| first direct | £0 (first direct) | £0 | £0 |
| Starling | £0 (Starling) | £0 (within £300 a day) | £0 |
| Monzo (main account) | £0 (Monzo) | £0 (EEA, unlimited) | £0 |
| Chase UK | £0 (Chase) | £0 (within £500 a day) | £0 |
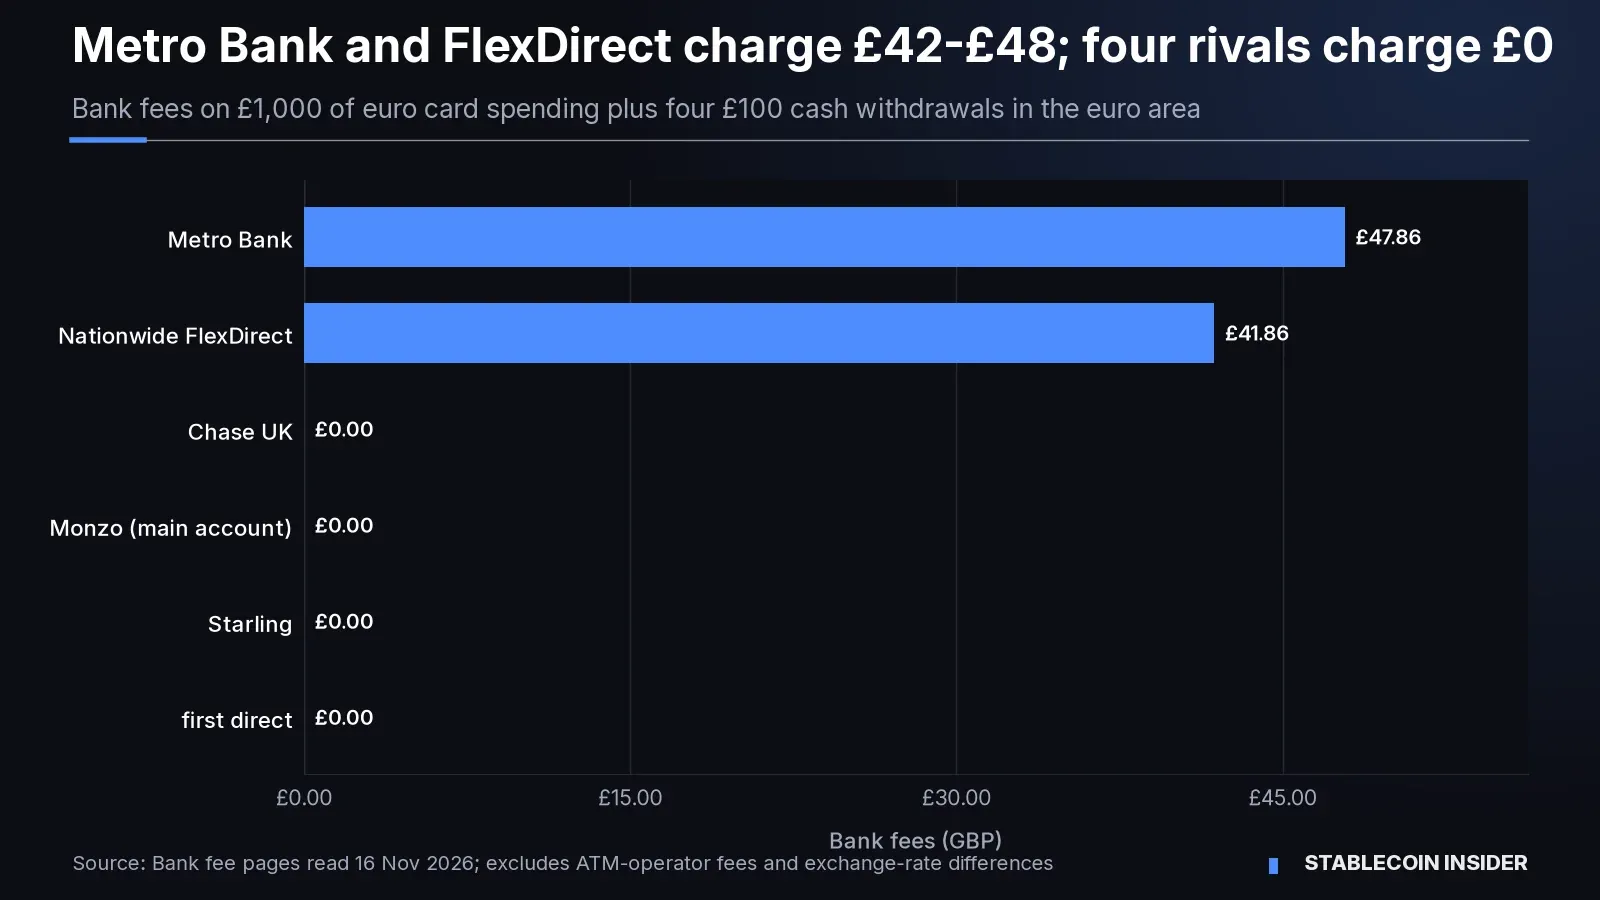
The totals exclude fees charged by ATM operators, which several of these banks warn may apply, and any difference in the exchange rate used. In this example, a one-off £175 or £210 switch payment is larger than a year of foreign fees, but someone who travels often keeps paying the 2.99% every year.
Is my money safe at Metro Bank during the sale process?
Your money at Metro Bank is protected in the same way during the sale process as before it. Metro Bank PLC is authorised by the Prudential Regulation Authority, and eligible deposits are covered by the FSCS up to £120,000 per eligible person, including current, savings and fixed-term accounts (Metro Bank; FSCS). Joint accounts are covered up to £120,000 for each holder, and temporary high balances such as house-sale proceeds can be covered up to £1.4 million for six months.
A takeover would only affect the limit if a buyer later moved Metro Bank's deposits into a banking licence you already use. In that case, PRA rule 19.1 requires at least one month's notice and, where your cover falls, a three-month window to withdraw or move the excess without penalty (PRA Rulebook). The Bank of England has confirmed that withdrawal right applies when two separately licensed banks become one (Bank of England PS7/23). No such transaction has been announced.
The same shared-licence rule matters when you choose an alternative. first direct shares its £120,000 limit with HSBC UK, HSBC Private Bank and M&S Bank (first direct). FSCS deposit cover applies to UK banks, building societies and credit unions, and the FSCS says it cannot protect e-money or payment services firms (FSCS). If you are weighing non-bank places to hold money, our guide to stablecoin savings accounts covers custody and risk separately.
How do you switch from Metro Bank without missing payments?
You switch from Metro Bank without missing payments by using the Current Account Switch Service, which moves your balance, Direct Debits and standing orders and closes the old account on a date you choose. Pay.UK runs the service, and the Current Account Switch Guarantee refunds any charges or interest caused by a switching error (Current Account Switch Service).
- Open the new account and pass its identity checks. Have your Metro Bank sort code and account number ready.
- Request the switch with the new bank and pick a weekday switch date at least seven working days away (CASS).
- Do not set up new payments on the Metro Bank account in the final seven working days; set them up on the new account instead (CASS FAQ).
- Meet the switch-offer conditions on time: 31 days for Nationwide's £175, 45 days for first direct's £210 (Nationwide; first direct).
- Keep using your Metro Bank card until the switch date. Afterwards, payments sent to the old account are redirected and the sender is told your new details (CASS FAQ).
A full switch closes your Metro Bank current account. If you want to keep it open, you can move payments yourself, but you lose the guarantee and, at Nationwide and first direct, the switch payment (CASS FAQ).
Sending money abroad from your new account? See how Wise and Revolut compare on fees and limits, or our Western Union alternatives for remittances. No Stablecoin Insider hub covers UK current accounts yet, so this guide stands alone.
FAQ
Is Metro Bank closing down?
Who is buying Metro Bank?
Can I keep my Metro Bank savings while switching my current account?
Does a joint account get more FSCS protection?
Stablecoin Insider's verdict on Metro Bank alternatives
Our pick for Metro Bank customers who want a branch is Nationwide FlexDirect: a large branch network with a commitment to 2030, no monthly fee and £175 for switching (Nationwide; Nationwide). If you rarely visit a branch, first direct pays the most to switch and removes card fees abroad (first direct). Choose Starling for 24/7 support and travel, Monzo for budgeting and cheap cash deposits, and Chase UK for cashback. There is no deposit-safety reason to rush: protection at Metro Bank is unchanged by the sale process (FSCS).
Sources: Metro Bank Holdings: Strategic Review and Formal Sale Process (RNS); Investing.com; Metro Bank Q3 2026 trading update; Metro Bank Current Account; Metro Bank: using my card abroad; Metro Bank store opening hours; FSCS protection checker; PRA Rulebook instruments 2023 (Depositor Protection 19.1); Bank of England PS7/23; Nationwide FlexDirect; Nationwide card fees abroad; Nationwide branch promise; first direct 1st Account; first direct cash and cheques; Starling current account; Starling travel; Starling Help: cash deposits; Monzo current accounts; Monzo travel; Chase UK; Chase UK: travelling with Chase; Current Account Switch Service; CASS common questions. All read on 16 November 2026.
This content is provided for informational and educational purposes only and doesn't constitute financial, investment, legal or tax advice. Fees, switch offers, interest rates and eligibility for Metro Bank, Nationwide, first direct (HSBC UK), Starling, Monzo and Chase UK (J.P. Morgan Europe Limited) were read from their own pages on 16 November 2026, apply to UK personal current accounts in GBP, and can change or be withdrawn at each bank's discretion. Overdrafts and offers are subject to status. Check the bank's own terms before you apply or switch.