Table of Contents
The best Chase Bank alternatives for most people are Capital One 360 Checking if you want no monthly fee, no overdraft fees and some in-person help, Charles Schwab Bank Investor Checking or the Fidelity Cash Management Account if you travel or already invest, and SoFi Checking and Savings or Ally Spending if you are happy with an app-only bank. Bank of America Advantage SafeBalance suits people who still want a big branch bank. Fees were read from each provider's own pages on 18 November 2026.
People are looking because Chase went down. On Monday, 16 November 2026, JPMorgan Chase said a "software bug in on-premise hardware systems" slowed transactions, said it was not cyber-related, and said transactions were posting normally by about 6:30 p.m. ET (NBC News). "Chase bank" then drew more than 1 million US searches on Google Trends over the past week. Our report on the outage covers what happened.
Last updated: 18 November 2026. Fees and terms re-checked against each provider's own pages on this date.
Key Takeaways
- Chase Total Checking costs $15 a month unless you meet one of four waivers, such as $500 in qualifying electronic deposits. Zelle, cash, checks and wires do not count toward that $500 (Chase fee schedule).
- Chase charges $3 per non-Chase ATM withdrawal in the US, $5 abroad and 3% on foreign-currency card use, effective 15 November 2026 (Chase).
- Capital One 360, Ally, SoFi, Schwab and Fidelity list no monthly account fee. Schwab and Fidelity also refund ATM operators' fees worldwide (Schwab; Fidelity).
- In our worked example, a customer who misses Chase's waiver pays $384 a year in Chase's own fees, against $0 at four of the six alternatives.
- Moving your paycheck away from Chase can switch on the $15 fee, so close or empty the account once the move is done.
Why are people looking for Chase Bank alternatives?
People are looking for Chase Bank alternatives because of the 16 November outage. Some Chase customers received the message "Some services aren't available," and one customer told CBS he could not deposit a check at a Dallas branch (CBS News). Chase said other banks were slowed only where they were party to a transaction with Chase (NBC News).
NBC reported that Chase has about 94 million US customer relationships and did not say how many were affected (NBC News). For many of those customers the real question is whether to keep all their money in one bank. Fees are the other reason: Chase's monthly fee and ATM charges only disappear if you meet its conditions.
Switching banks does not make outages impossible. We have no data showing any account here is less likely to fail. What a second account at an unrelated bank gives you is a way to pay and get cash while one bank is down.
Chase Bank alternatives at a glance
The table compares Chase Total Checking, the reference row, with six US alternatives on monthly fee, the provider's own ATM fees, foreign-currency card fees and access. Each cell links to the page it was read from on 18 November 2026.
| Account and access | Monthly fee | Provider ATM fees | Foreign card fee |
|---|---|---|---|
| Our pick: Capital One 360 Checking Online, branches and Cafés | $0, no minimum (Capital One) | $0; 70,000+ fee-free ATMs (Capital One) | None (Capital One) |
| Reference: Chase Total Checking 14,000+ ATMs, 5,000 branches (Chase) | $15, or $0 with a waiver (Chase) | $3 US, $5 abroad at non-Chase ATMs (Chase) | 3% (Chase) |
| Schwab Bank Investor Checking Needs a linked Schwab One brokerage account | $0 (Schwab) | Unlimited ATM fee rebates worldwide (Schwab) | None (Schwab) |
| Fidelity Cash Management Brokerage cash account, not a bank | $0 (Fidelity) | ATM fees refunded globally (Fidelity) | None (Fidelity) |
| SoFi Checking and Savings App only, no branches | $0 (SoFi) | $0 from SoFi (SoFi); 55,000+ Allpoint ATMs (SoFi) | $0 on POS (SoFi) |
| Ally Spending Account App only, no branches | $0 (Ally) | $0 from Ally; up to $10 a cycle refunded (Ally) | Up to 1% (Ally) |
| BofA Advantage SafeBalance Branch bank; no paper checks | $4.95, or $0 with a waiver (BofA) | $2.50 US, $5 abroad at non-BofA ATMs (BofA) | 3% (BofA) |
Two patterns stand out. Every alternative except Bank of America drops the monthly fee without conditions, while Chase and Bank of America charge 3% on card spending in foreign currencies (Chase; BofA). And only Schwab and Fidelity refund ATM operators' own fees outside the US. Ally's $10 refund covers US ATM operators only (Ally).
How much would you save by leaving Chase?
You would save up to $384 a year by leaving Chase in our example, but only if you do not meet any of Chase's fee waivers. The example uses three explicit assumptions and counts only the fees each provider charges itself.
- No Chase waiver is met in any month, so the $15 monthly fee applies all year: $180 (Chase). New accounts are not charged for the first two statement periods (Chase); we ignore that.
- Four withdrawals a month (48 a year) at US ATMs outside the provider's network: $3 each at Chase, $144 (Chase).
- $2,000 a year spent by debit card in foreign currencies: 3% at Chase, $60 (Chase).
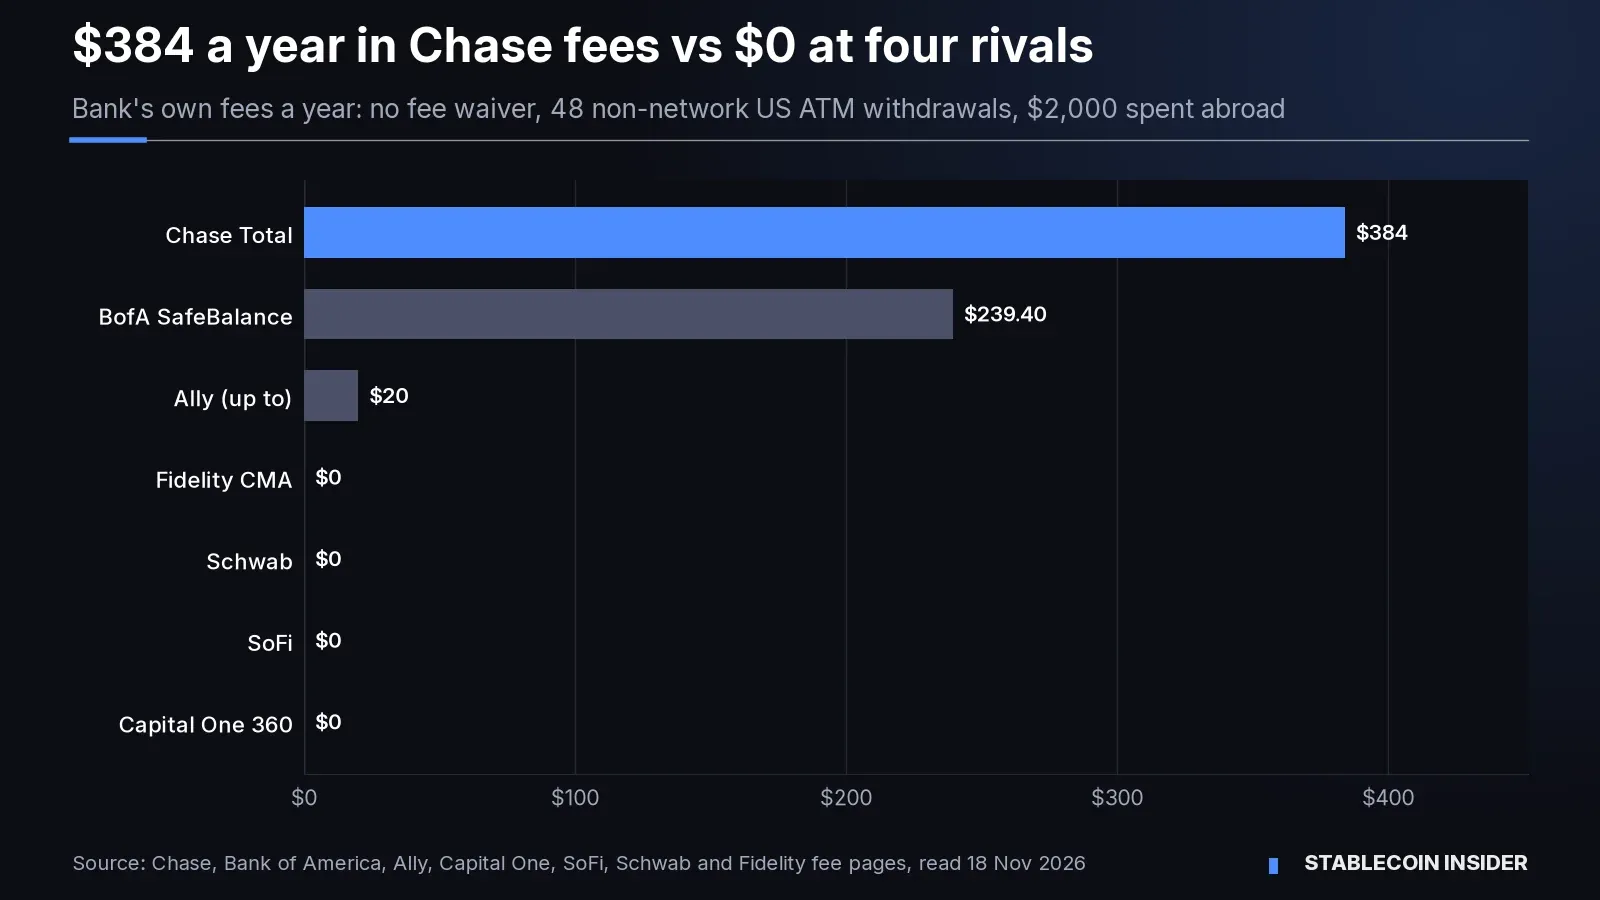
Bank of America SafeBalance comes to $239.40: $59.40 in monthly fees, $120 in ATM fees at $2.50 each and $60 in 3% foreign fees (BofA). Its non-Bank of America ATM fee rises to $3.00 on 19 February 2027, which would add $24 a year. Ally's only charge is its international fee of up to 1%, so at most $20 (Ally).
The figures leave out fees that ATM owners add themselves and the card network's exchange rate, because those depend on where you are. Schwab and Fidelity refund ATM owners' fees, and Ally refunds up to $10 a statement cycle in the US. If you already get $500 a month in direct deposits at Chase, your Chase cost in this example falls to $204.
Which Chase Bank alternatives are best in 2026?
The best Chase Bank alternatives in 2026 depend on whether you need a branch, travel abroad or want interest on your cash. Each profile says who it suits and what it does better or worse than Chase.
1. Capital One 360 Checking: best overall Chase alternative
Capital One 360 Checking is the best overall Chase alternative for people who want no fees and some in-person help. It has no monthly fee, no minimum balance and no overdraft fees, plus 70,000+ fee-free Capital One, MoneyPass and Allpoint ATMs (Capital One). It pays 0.10% APY on all balance tiers, rates effective 18 November 2026.
Capital One charges no extra fees when you use the 360 debit card abroad (Capital One). You can visit Capital One branches and Cafés, though Capital One says Cafés do not offer the same services as branches (Capital One).
Worse than Chase: no-fee overdraft is only available once you deposit at least $250 in two of the previous three calendar months, so new accounts start without it (Capital One). Capital One does not list a branch count on the page, and Chase lists 5,000 branches (Chase).
- Pros: no monthly, overdraft or foreign fees; large fee-free ATM network; in-person help at branches and Cafés.
- Cons: only 0.10% APY; out-of-network ATM owners may still charge; no-fee overdraft needs regular deposits.
2. Schwab Bank Investor Checking: best for travelers
Schwab Bank Investor Checking suits people who travel or withdraw cash at many different ATMs. It has no monthly service fees, no foreign transaction fees and unlimited ATM fee rebates on cash withdrawals worldwide (Schwab). Overdraft protection draws on your linked Schwab One brokerage account, and Schwab does not charge a fee for it.
Worse than Chase: you can only open it as a linked account with a Schwab One brokerage account, though that account has no minimum balance or funding requirement (Schwab). If overdraft protection draws on margin, it can create a margin loan with interest.
- Pros: no monthly or foreign fees; ATM fees rebated worldwide; cash moves to a linked Schwab brokerage account, usually in seconds.
- Cons: requires a brokerage account; rebates exclude dynamic currency conversion and non-withdrawal fees.
3. Fidelity Cash Management Account: best for investors
The Fidelity Cash Management Account suits people who already invest with Fidelity and want their spending cash to earn more. It has no monthly fees or minimums to open, no foreign debit transaction fees and reimburses ATM fees charged by other institutions worldwide (Fidelity). Fidelity showed a 3.57% 7-day yield for its SPAXX money market fund as of 17 November 2026 for cash held there.
Worse than Chase: Fidelity is not a bank. Cash swept to program banks is FDIC-eligible, but money in the SPAXX money market fund is not FDIC-insured and can lose value (Fidelity). Fidelity says the account is available only to Fidelity customers.
- Pros: no monthly or foreign fees; global ATM fee reimbursement; money market yield option.
- Cons: not a bank; money fund balances are not FDIC-insured; a quarterly fee of up to $5 can apply to small idle balances.
4. SoFi Checking and Savings: best for direct deposit savers
SoFi Checking and Savings suits people who can send their paycheck to an app-only bank and want interest on savings. It charges no monthly, minimum balance or overdraft fees (SoFi). Savings earn 3.30% APY with eligible direct deposit or $5,000 in deposits every 31 days, otherwise 0.80%; checking earns 0.50% APY (SoFi).
SoFi does not charge for ATM withdrawals and lists $0 for domestic and international card purchases (SoFi). It has 55,000+ fee-free Allpoint ATMs (SoFi). You can opt in to extra FDIC coverage of up to $3 million through partner banks (SoFi).
Worse than Chase: SoFi has no physical branches (SoFi), and cash deposits through its partners can cost up to $4.95 each (SoFi).
- Pros: no account fees; 3.30% savings APY with eligible direct deposit; extra FDIC coverage by opting in.
- Cons: no branches; best rate needs direct deposit; fees for cash deposits.
5. Ally Spending Account: best for app-only banking with US ATM refunds
The Ally Spending Account suits app-first customers who mainly use cash in the US. It has no monthly maintenance fee, overdraft fee or minimum balance, 24/7 human support and 75,000+ no-fee Allpoint and MoneyPass ATMs (Ally). Ally charges no ATM fee itself and refunds up to $10 a statement cycle in fees from US ATM operators (Ally). It pays 0.10% APY under $15,000 and 0.25% from $15,000 (Ally).
Worse than Chase: Ally has no branches (Ally). Its international transaction fee is up to 1%, and it does not refund fees from ATM operators outside the US (Ally).
- Pros: no monthly or overdraft fees; US ATM refunds up to $10 a cycle; 24/7 support.
- Cons: no branches; up to 1% abroad; low checking APY.
6. Bank of America Advantage SafeBalance: best if you want a big branch bank
Bank of America Advantage SafeBalance suits people who want a large branch bank but a cheaper, simpler account than Chase Total Checking. Its monthly fee is $4.95, waived if an owner is under 25 or you keep a $500 minimum daily balance, and it has no overdraft item fees (BofA). The minimum to open is $25.
Worse than Chase: it charges the same 3% on foreign-currency card use and $2.50 per non-Bank of America ATM withdrawal in the US, rising to $3.00 on 19 February 2027 (BofA). You cannot write paper checks. Bank of America customers also reported problems on 16 November, though the bank told CBS its systems were operating normally (CBS News).
- Pros: large branch bank; low, avoidable fee; no overdraft item fees.
- Cons: 3% foreign fee; ATM fees outside its network; no paper checks.
How do you switch from Chase without missing a payment?
You switch from Chase without missing a payment by running both accounts side by side for one or two statement cycles. The order matters because of Chase's fee rules.
- Open the new account and confirm it is FDIC-insured, or for Fidelity, how your cash is held. FDIC cover is $250,000 per depositor, per insured bank, for each ownership category (FDIC).
- Move your paycheck and benefits first. Once direct deposits leave, Chase's $500 waiver lapses, and you need a $1,500 daily balance or another waiver to avoid the $15 fee (Chase).
- Move bill payments, subscriptions and card autopays one by one, and check each one posts from the new account.
- Leave enough at Chase to cover anything still pending. Chase charges $34 per overdraft above $50, up to three a day (Chase).
- Close the Chase account, or keep a small, fee-free balance there as a backup if you meet a waiver.
Should you stay with Chase instead?
You should stay with Chase if you meet a fee waiver easily and value its branch and ATM network. Chase lists more than 14,000 ATMs and 5,000 branches, and the monthly fee is $0 with $500 in qualifying electronic deposits, a $1,500 daily balance or $5,000 across linked accounts (Chase). Its Overdraft Assist means no overdraft fee if you are overdrawn by $50 or less at the end of the business day.
If the outage is your only concern, adding a no-fee account elsewhere as a backup may be enough. Capital One 360, SoFi or Ally cost nothing to keep open on their published terms.
Our verdict on Chase Bank alternatives
Capital One 360 Checking is our pick for most people leaving Chase. It removes the monthly, overdraft and foreign fees without conditions, has a large fee-free ATM network and still offers some in-person help (Capital One; Capital One). Its weakness is a low 0.10% APY.
If you travel, Schwab or Fidelity remove ATM costs worldwide. If you want interest and can move your paycheck, SoFi fits. If you need a branch bank, Bank of America SafeBalance is cheaper than Chase Total Checking but keeps similar ATM and foreign fees.
Moving money between your accounts? See our Zelle vs Venmo comparison and Venmo vs Cash App guide. If you hold digital dollars as well, read whether stablecoins are FDIC insured and how Revolut plans to combine FDIC-insured accounts with stablecoins. No Stablecoin Insider hub covers US checking accounts yet, so this guide stands alone.
FAQ
Is Chase Bank still down?
Is my money safe at Chase after the outage?
Does Zelle work with Chase alternatives?
Which Chase alternative has no foreign transaction fees?
Can I keep a Chase account open as a backup for free?
Sources: Google Trends, US trending searches, past 7 days; NBC News; CBS News; Chase Total Checking; Chase Additional Banking Services and Fees, effective 15 November 2026; Capital One 360 Checking; Capital One international ATM fees; Capital One ATMs; Schwab Bank Investor Checking; Fidelity Cash Management Account; SoFi Checking and Savings; SoFi Bank fee sheet; Ally Spending Account; Ally ATMs; Ally Debit Card Agreement, effective 23 September 2026; Bank of America Advantage Banking; Bank of America Personal Schedule of Fees, effective 13 November 2026; FDIC: Understanding deposit insurance. All read on 18 November 2026.
This content is provided for informational and educational purposes only and doesn't constitute financial, investment, legal or tax advice. Fees, rates and eligibility for JPMorgan Chase, Capital One, Charles Schwab, Fidelity, SoFi, Ally and Bank of America were read from their own pages on 18 November 2026, apply to US personal accounts in USD, and can change at any time. Rates are variable. Money market funds are not bank deposits and can lose value. Check each provider's current terms before you switch.